Find the questions before they become the lender's questions.
Before the lender reads your business, Ziyon reads it first. We review your accounts, cash flow, existing debt and funding story before a material borrowing decision, refinance or facility review.
Earlier visibility. Time to act. No promise of approval.
“If profit is rising, why is cash falling?”
“Why are customers taking longer to pay?”
You ask the bank for £1m.
Then the questions begin.
The expensive time to discover a weakness in your funding case is after the credit process has started.
Ziyon asks every one of these.
Accounts and forecast submitted
“Why have debtor days increased?”
“What explains this related-party balance?”
“Profit is increasing. Why is cash falling?”
“What if sales miss the forecast?”
Revised information requested
Ziyon's job is to ask those questions before Day 1.
Illustrative sequence; actual lender timing varies.The question is the same.
Your options aren't.
Before submission, you can explain a balance, test a forecast, correct an inconsistency or reconsider the timing. Inside a live process, the same questions can cost time, momentum and negotiating flexibility.
Ziyon moves the point of discovery earlier, while the answers are still yours to prepare.
A material decision.
A reason to look earlier.
Typically for established UK companies with £2m–£20m turnover and around £500k+ borrowing or facility exposure. Complexity and consequences matter more than a threshold.
New borrowing, refinancing, acquisition or expansion. Understand the questions before committing to the process.
Spot changes in cash generation, headroom and maturity risk before the next lender review.
Examine what the evidence can explain before you resubmit the same case.
Simple, low-value, non-urgent borrowing may not need specialist preparation. See when Ziyon is worth considering.
Credit Snapshot
What is credit likely to question?
What should you address first?
An independent read of your actual documents, with the three most material issues identified where present, and a clear first priority.
You are buying professional judgement, not just a score. If the file needs preparing: Audit from £500. Once debt is drawn: Credit Watch from £300 a month.
One set of accounts.
Two ways to read it.
“We've returned to profit.”
Manufacturing · turnover c.£11.7m · anonymised public file“What funded the recovery, and can it happen again?”
The terms of a £2.1m related-party balance that fell during the year, and why stock now takes 107 days to turn instead of 71.
Raised on Day 14, it is a query on the file. Addressed before Day 1, it is part of the story management tells.
Public-file analysis only. Not a client engagement or a full credit verdict.
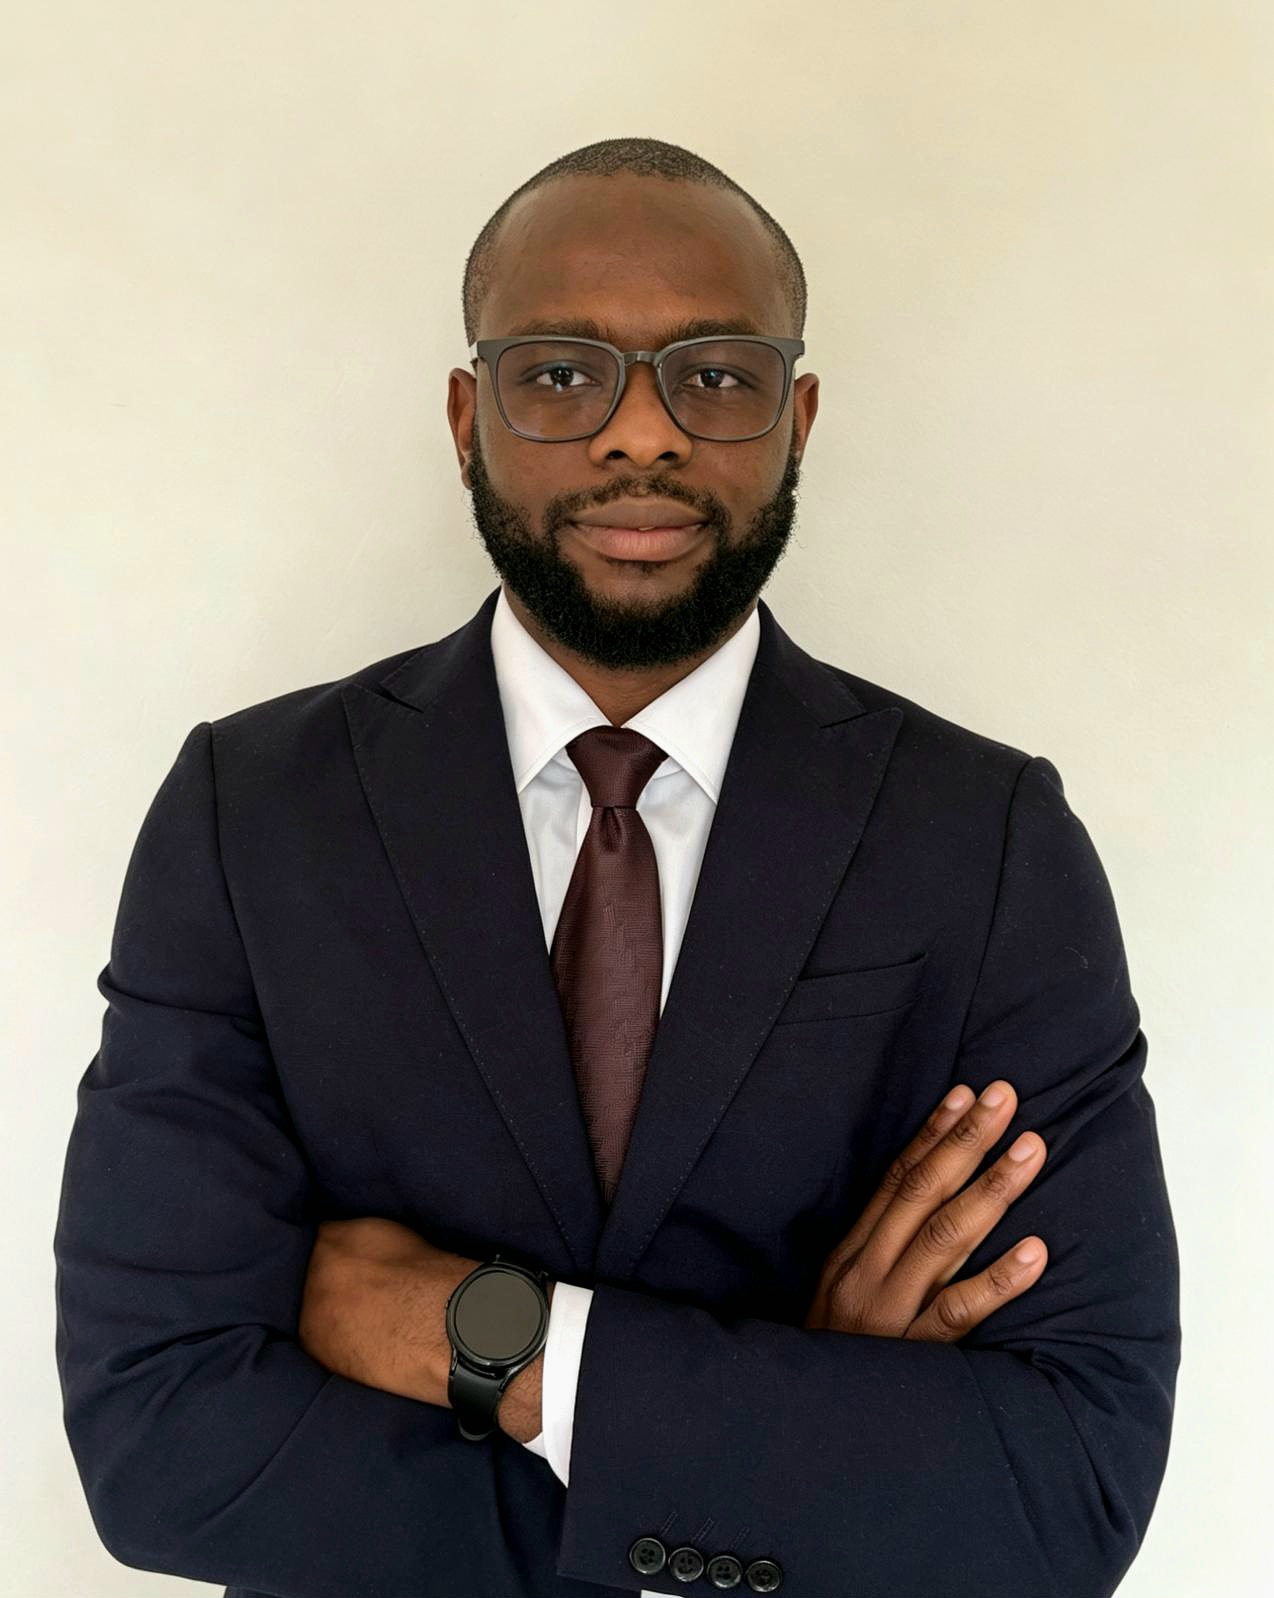
Samuel Lotechukwu, ACA
A credit analyst on your side of the desk. With the eyes of the committee.
What Ziyon
does not do.
Engaged on the borrower's behalf, for independent credit analysis and preparation. The lender makes the decision. Ziyon never acts for both sides of the same transaction.
Find the questions while you still have options.
Start with an independent read of your file. Two pages. Five business days. £150.