The questions Ziyon asks are the ones it used to ask from the other side of the desk.
Owners usually meet credit judgement only once it is being applied to them. Ziyon exists to bring it forward, to the borrower's side, while there is still time to respond.
The founder
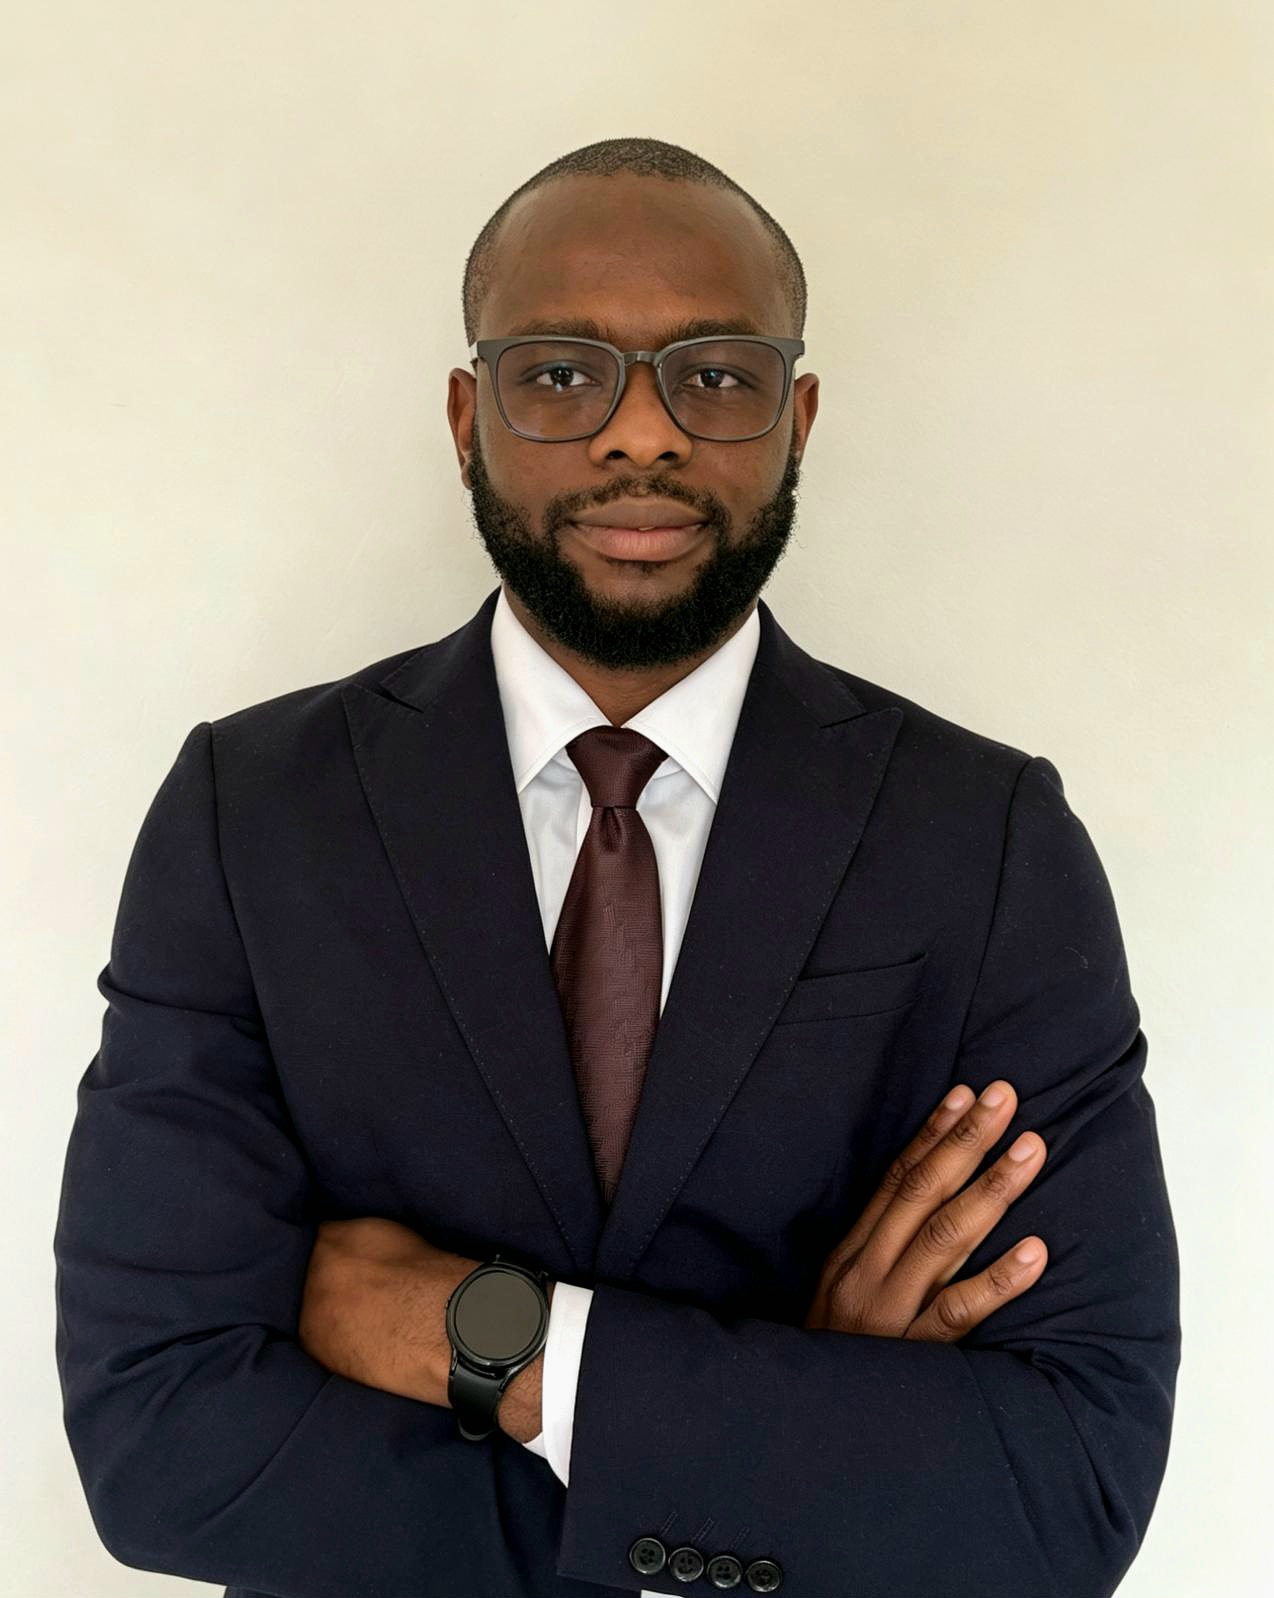
Samuel Lotechukwu, ACA
Ten years in finance. Three years assessing corporate credit.
Samuel's experience includes reading corporate financial information, preparing credit memos and presenting cases to credit committee, with larger cases reaching the Board on memos he prepared.
He managed a corporate portfolio of more than $350m with no non-performing loans. That experience informs the questions Ziyon asks; it is not a promise about a future lending outcome.
The purpose is practical: bring the same discipline to the borrower's preparation, while management can still decide how to respond.
A credit read asks whether the business can repay, what could interrupt repayment and whether the documents support the story.
Ziyon uses five lenses (character, capacity, capital, collateral and conditions) to organise that challenge. Every assessment states the basis used and what the available information cannot establish.
The method helps make the work consistent. It does not make Ziyon the lender or turn a written assessment into an approval.
Independence
One side of the desk, per transaction.
Ziyon is engaged on the borrower's behalf, and the analysis is written for the borrower.Where Ziyon works with brokers or lenders, any introduction, and any fee attached to it, is agreed and disclosed in writing.Ziyon never acts for both sides of the same transaction. If a second engagement on the same deal arrives, we decline it, whichever came first.Ziyon does not lend, arrange finance or negotiate terms, and operates outside the FCA regulated perimeter.
What owners ask before they begin.
No. Ziyon does not arrange finance or negotiate terms. We prepare and challenge the credit case; you or your broker decide where it goes. Where an introduction is made, it is disclosed in writing, and Ziyon never acts for both sides of the same transaction.
No. Your accountant keeps your numbers accurate and compliant. Ziyon reads those same numbers the way a credit analyst will: for serviceability, leverage, concentration and the gaps a committee circles. The two roles complement each other.
You can apply directly, and for small or simple borrowing you probably should. Where the event matters, a question found inside a live process can cost time, momentum and options. Ziyon moves the point of discovery earlier.
No, and anyone who promises it is misleading you. The lender makes the decision. What changes is what the file gives them to decide on.
No. We work alongside them, and the prepared file goes back through them.
Yes. We examine the additional credit questions created by group structure, ownership evidence, cross-border cash flows, FX exposure and repatriation risk. These files usually sit in the Premium tier of the Audit.
If a material credit event is approaching and the questions are not yet clear, start with the £150 Credit Snapshot. If you already know the file needs work, book an Audit scoping call. If you are unsure whether you need us at all, try the free Funding Preflight.
Before the next credit decision
Find the questions while you still have options.
Start with an independent read of your file. Two pages. Five business days. £150.